When one down payment dwarfs the other
It usually shows up in a plain spreadsheet: one person can bring $140,000 to closing, the other can scrape together $25,000, and the house you both want doesn’t wait for feelings to catch up. The bigger check starts to feel like a quiet claim on the future, but the mortgage application treats you as two names on one loan, not two separate ledgers. Meanwhile the cash-poor partner is often taking on a different constraint—higher monthly payment stress, or draining an emergency fund to participate at all.
That mismatch is the first moment worth slowing down. If you don’t decide what the large down payment “buys” in ownership terms, you’re effectively choosing the default: whoever can argue loudest later. And later usually arrives with a deadline—refinance rates, a job move, a breakup, or a repair bill that lands right after closing.
Your first expectation: split it 50/50 and move on
The first instinct is usually to make it “clean”: two people, one home, split everything down the middle and stop talking about it. It sounds fair in a relationship sense, and it reduces paperwork when you’re already juggling inspection negotiations, insurance quotes, and a closing date that keeps creeping closer. There’s also a social pressure here—asking for a different split can feel like turning a shared plan into a scorecard.
But the 50/50 idea is less of a decision than a refusal to price the imbalance. If one person is wiring most of the cash at closing, calling the equity even is basically an undocumented gift that only feels invisible while things are stable. The smaller contributor may be counting on “we’ll square it up later” through higher monthly payments, sweat equity, or taking on more of the household risk when reserves get thin. None of that is automatic, and none of it is specific enough to survive a hard month or a hard conversation.
Reality check: the lender doesn’t track fairness
The next surprise tends to hit when the loan officer sends the paperwork and it’s all blunt categories: borrower, co-borrower, joint and several liability. The lender is underwriting repayment risk, not refereeing who “put in more.” If both of you are on the mortgage, the bank can pursue either of you for the full payment after one missed month, even if the other person supplied most of the down payment. That’s the constraint hiding under the romance of “we’re doing this together”: the liability is shared even when the cash wasn’t.
Title doesn’t cleanly fix it either. You can take title in equal shares, or in unequal shares, but that choice mainly controls how you own the asset—not how the lender views the debt. And if you leave one person off the mortgage to “keep it simple,” you’ve traded one problem for another: the non-borrower may have ownership without loan responsibility, or loan responsibility without ownership, depending on how you structure it. Either way, the bank’s records won’t reconcile your internal fairness math when something changes fast.
Choose a baseline ownership split you can defend
So the first “fairness” decision isn’t the monthly split yet—it’s what ownership percentages start at on day one, when the deed gets recorded and the down payment becomes locked in. The baseline has to survive scrutiny later, when someone is tired, angry, or under a move-out deadline. A clean option is pro-rata to cash invested at closing (down payment, closing costs, prepaid items you agree to count), but that forces a hard call on what counts as “cash in” and what doesn’t. Another common baseline is still 50/50, but only if you explicitly treat the excess down payment as a separate claim, not a vague sacrifice.
In practice, the defensible middle ground is often: return contributions first, then split remaining equity by an agreed ratio. It matches how a buyout conversation actually happens—“I get my $140,000 back, then we divide what’s left”—and it reduces the fight over whether early appreciation was “earned” by one person’s check or both people’s risk. The constraint is timing: you need a method to value the home (appraisal vs. sale price) and a deadline for funding a buyout.
Decide how future payments change the math
Once the baseline is set, the next disagreement usually isn’t philosophical—it’s accounting. If one person is covering more of the monthly cost, decide what actually moves ownership. A common mistake is treating the entire payment as “equity.” Only principal paydown increases equity; interest, property taxes, insurance, and most utilities are consumption. If you’re trying to “catch up” for a smaller down payment, over-weighting interest can quietly overcompensate the higher payer while still leaving the other person on the hook for the full debt if something goes sideways.
From here, you’re choosing between simplicity and precision. Simplicity: keep the ownership split fixed, and treat any uneven monthly contributions as a reimburse-at-sale ledger (often limited to principal only). Precision: true-up ownership over time based on cumulative capital contributions (down payment plus principal), which requires clean records and a rule for missed months. The right choice is the one you can still calculate under a deadline, not the one that sounds fairest today.
Stress-test the breakup, buyout, and ‘can’t pay’ scenarios
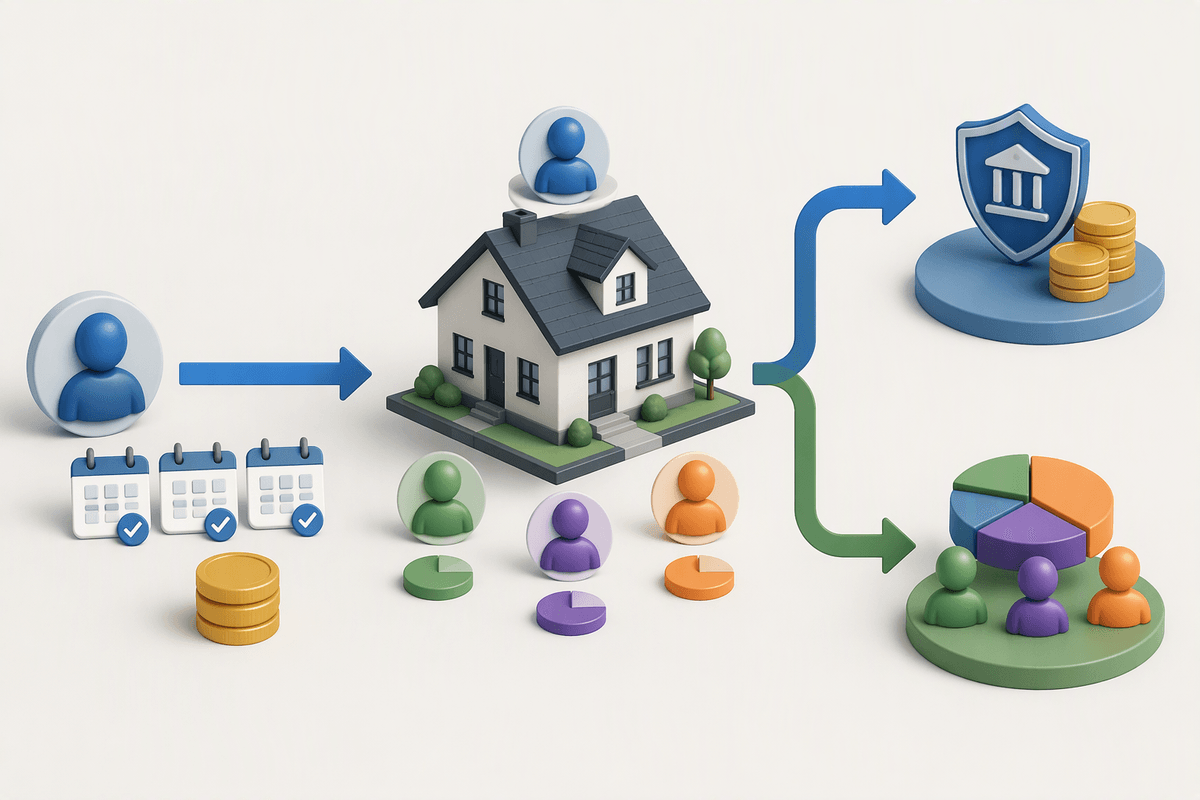
This is the part people skip because it feels like inviting bad luck, but it’s also the first time your formula meets a deadline. If one person wants out in year two, do you require a sale, or allow a buyout? If it’s a buyout, pin down the value trigger (independent appraisal versus an agreed agent opinion), who pays for it, and how quickly the remaining partner has to come up with cash. Without a clock, “I’ll buy you out soon” turns into months of shared liability and resentment.
Then run the ugly version: one person can’t pay for three months. Decide whether the other person’s covering payments is a loan, an equity credit (usually principal only), or neither. Also decide what happens if the home must be sold at a bad time—do contributions get returned first, or do you share the loss by the ownership split? The goal isn’t optimism; it’s having one path that still works when nobody has extra money.
Put it in writing before the mortgage is signed
At this point the numbers work on paper, but they won’t protect either of you if they live only in texts and good intentions. The practical constraint is timing: once you’re inside the closing window, everyone is optimizing for “get it done,” and last-minute edits to title, escrow instructions, or side agreements can stall the file. So treat the agreement as a closing deliverable, not a post-close cleanup project.
Keep it boring and checkable: your baseline split, what counts as a capital contribution, how principal credits are tracked, how value is set for a buyout, and a deadline for refinancing or sale if one person exits. Then match the paper to the structure (title vesting plus a co-ownership agreement, or a promissory note for the excess down payment). If it can’t be explained to a third party in one page, it’s probably not enforceable under stress.